
The checks below are general. They can help an adult reader organise available information, but they do not establish whether a withdrawal will be approved or when funds will arrive. A record may show what a website displayed at a particular point; it may not reveal what happened inside a payment system or a bank.
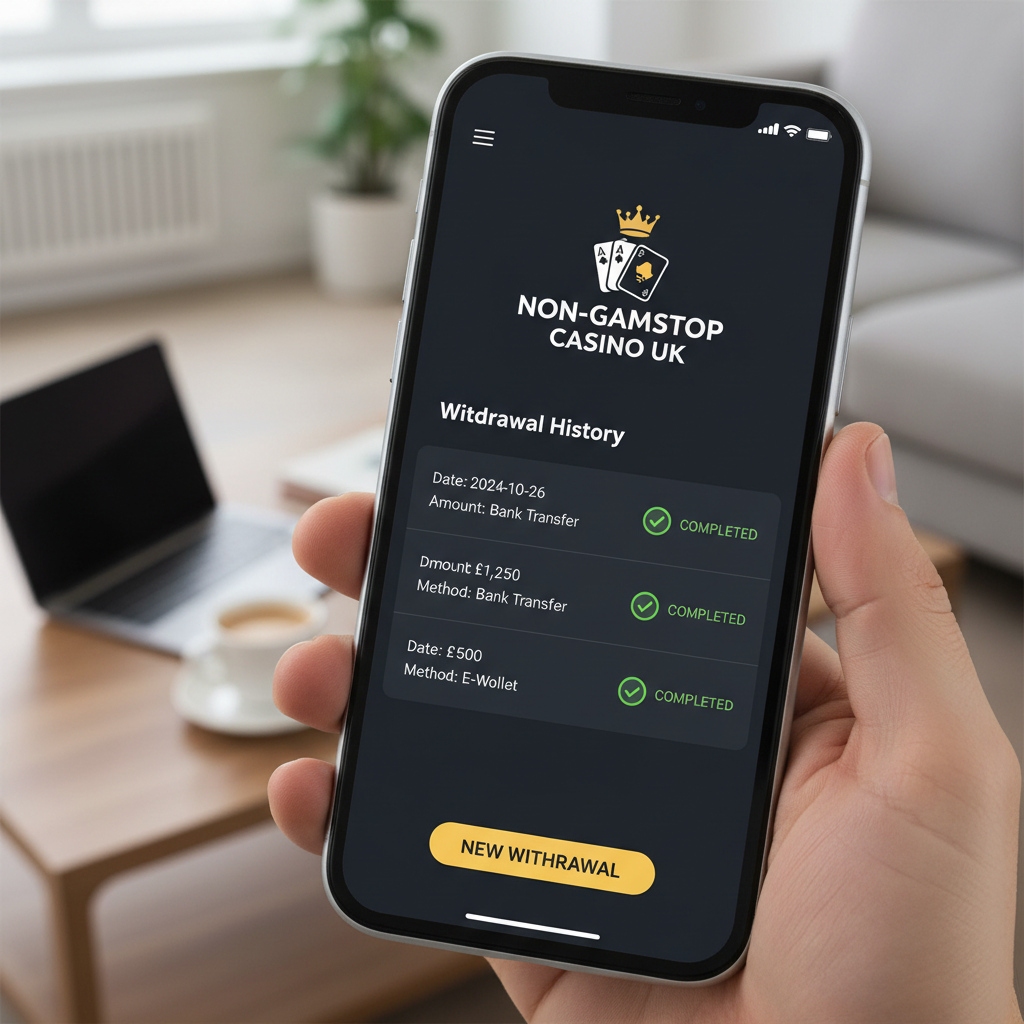
What withdrawal records can show
Start with records that relate to the same withdrawal. An account history, confirmation screen, email, or saved copy of the applicable terms may help identify the requested amount, the date shown, and any status message. Preserve the original wording where possible. If a screen is saved, note when it was captured and which account area it came from. Keep personal and payment details private when storing or sharing records.
These materials have limits. A request marked as submitted can establish that a request was recorded, but not that a payment was released. A displayed completion status may describe an operator-side step rather than confirmed receipt in an external account. A bank or payment account record can help check for a credit, but a missing entry alone does not identify the cause of a delay. No such records have been supplied for this article, so none of these statuses is an actual finding.
Consider whether every record refers to the same transaction. Amounts, dates, account references, and payment routes should be compared carefully, allowing for different date formats or time zones if those are shown. Avoid treating an unexplained difference as evidence of misconduct: first establish what each record measures and whether it refers to the same event.
Check the terms and timeline
Read the terms that applied when the withdrawal was requested, if a dated or otherwise identifiable copy is available. Look for the stated processing stages, any conditions that may affect a request, and the procedure for raising a question. Do not assume that a general page, an older saved copy, or a message about another transaction describes the terms that applied here. The applicable wording has not been provided in this review.
Build a timeline from records rather than memory alone. Separate the time the request was made, any later status changes, messages asking for information, replies, and any independently recorded payment receipt. If the displayed terms describe a processing estimate, record its wording as an estimate; do not convert it into a guarantee. If no estimate or applicable term can be verified, mark that point as unknown instead of filling the gap with a customary timeframe.
| Record type | What it may help establish | What it cannot establish alone |
|---|---|---|
| Account history or confirmation | A request or status displayed in the account | That funds reached an external account |
| Saved terms or policy text | The wording available in that copy | That the same wording applied at another time |
| Messages about the request | What was communicated and when | That an unrecorded action was completed |
| Payment account statement | Whether a matching credit appears in that account | The reason a credit is absent or delayed |
Compare the evidence
Compare sources by question, not by which one seems most convincing. A website record may be useful for the request and its displayed status; a message may clarify what information was requested; an account statement may show whether a credit appeared. Where records conflict, preserve both versions and note the difference. Do not alter an original record to make dates or amounts appear consistent.
A simple comparison can flag gaps without turning them into conclusions. Check whether:
- The amount and transaction reference, where shown, match across records.
- The dates are recorded in the same format and refer to the same stage.
- A stated condition or request for information is supported by a dated record.
- The terms being compared can be connected to the time of the withdrawal.
A missing document is a gap, not proof of either a valid or invalid decision. Likewise, one person’s account, if encountered elsewhere, would not verify another transaction or establish a general outcome. This checklist contains no customer accounts and does not report any tested withdrawal.
Document a delayed withdrawal
If a withdrawal appears delayed, make a clear, private record of what is known. Keep copies of relevant account screens, messages, the terms consulted, and payment-account entries. Note the date each item was saved and write a short chronology using neutral language, such as “status displayed” or “message received.” Avoid sharing passwords, full payment credentials, or unnecessary identity documents in informal channels.
If you contact a service about an existing transaction, use a contact method already verified through its own account or official materials, and keep a copy of the message and any reply. Ask for a specific explanation of the recorded status or the next documented step. This is a record-keeping suggestion, not confirmation that any particular support channel exists or that a reply will resolve the issue. No support details or customer outcomes have been verified for this review.
Where the response does not match the records, note the discrepancy and ask for clarification without making claims the evidence cannot support. If you choose to raise the matter through another appropriate channel, provide only relevant copies and retain the originals. Do not create multiple accounts or seek ways around self-exclusion. Logging out only ends an active session; it is not the same as requesting account closure or deleting an account. Anyone who has self-excluded and is worried about gambling should prioritise that protection rather than pursue access to gambling services.